How to Build an Emergency Fund: The Ultimate Beginner’s Guide to Financial Safety
A Beginner’s Guide to Creating an Emergency Fund
Have you ever woken up to the sound of your car engine grinding and not had the money saved up to cover the repair? Most people have, and it is a terrible feeling. This is usually the case with unexpected expenses. There is usually some level of shock that comes with the expense and is often worse than the expense itself.
An emergency fund helps minimize the level of shock you experience when an unexpected expense occurs. Without an emergency fund, an unexpected $800 expense will put you in a very difficult situation. With an emergency fund, an $800 expense is not as bad.
You don’t need to have a high income to start your emergency fund, and you don’t need to have a large amount of money to begin with. The first step to starting your emergency fund is understanding what an emergency fund is, roughly estimating how much you need, and setting up a system that helps you save money automatically.
What Is an Emergency Fund?
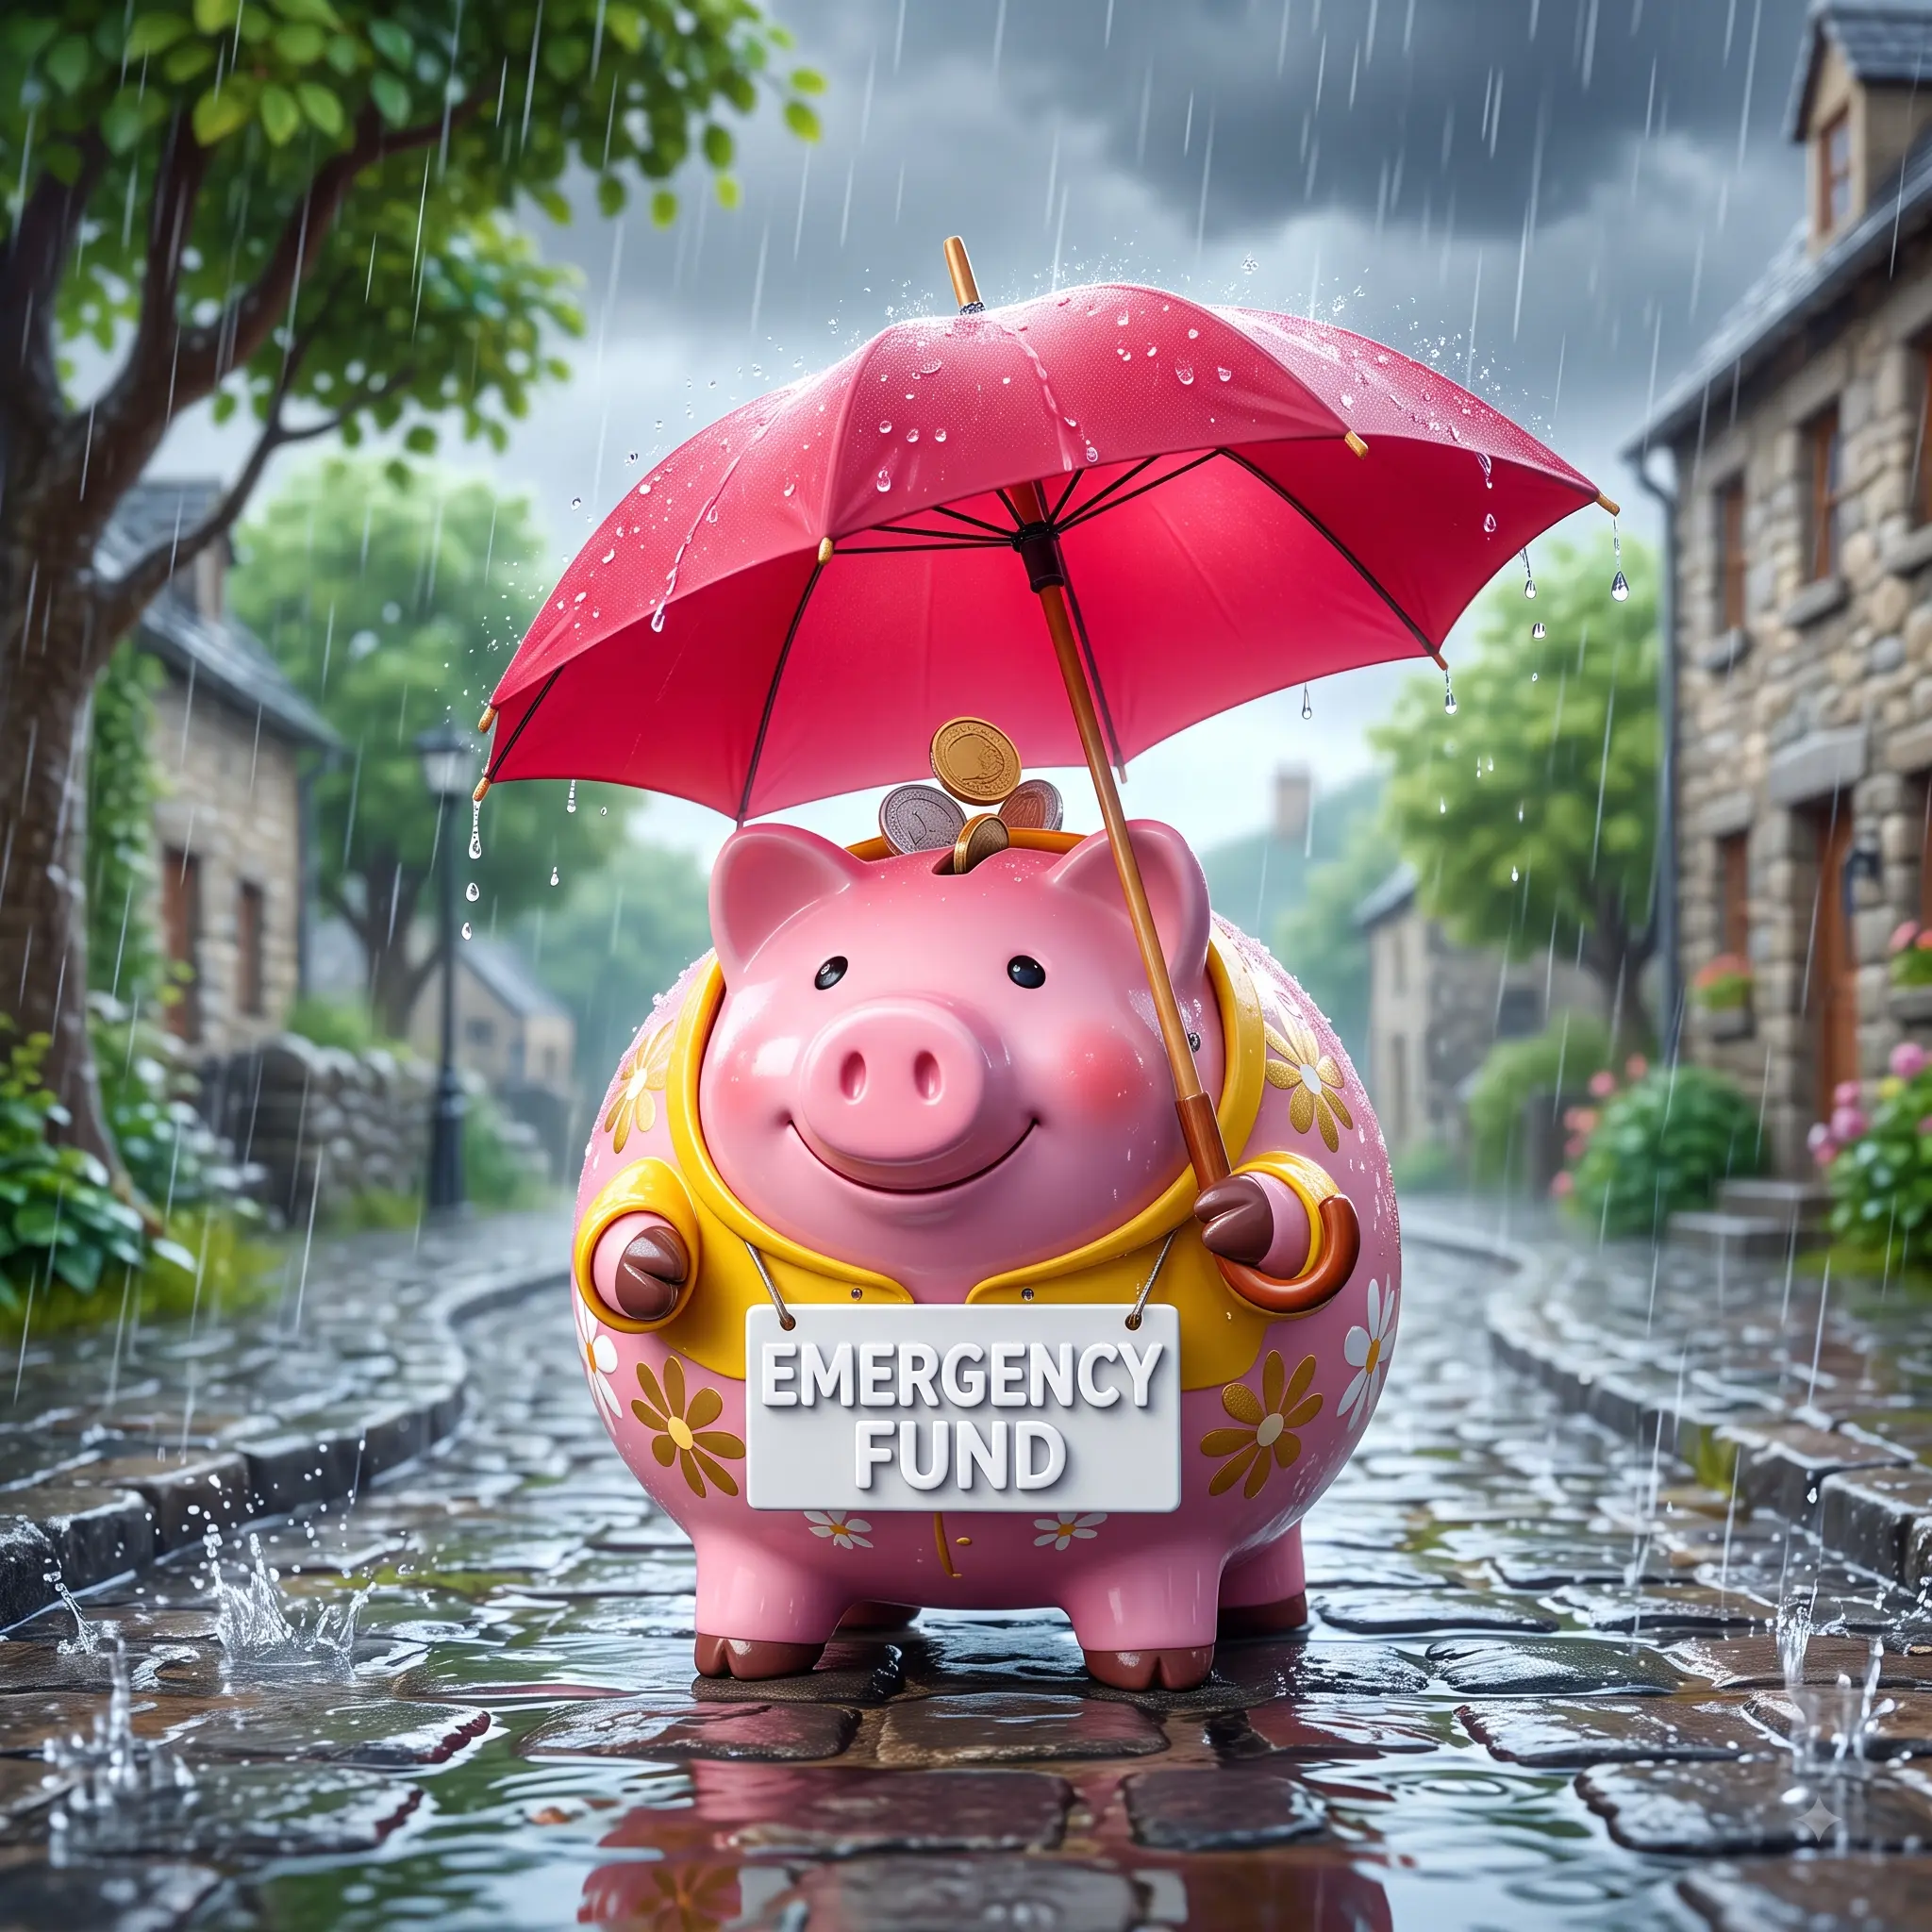
An emergency fund is money that you set aside to help you cover expenses that you never see coming. This money is set aside separately from the money that you save to go on vacation or to make a large purchase. The money in your emergency fund should not be touched unless absolutely necessary.
Let’s say your roof gets damaged in a storm and a contractor estimates $1,000 for the repair. If you don’t have the money saved, you might have to put the entire cost on a credit card and risk getting it meager months later. If you have the money saved, you can pay for the repair, put up with the inconvenience, and then save money again.
Emergency funds try to strike a balance between return and security. That is why the Consumer Financial Protection Bureau’s guidance on emergency savings states that it is important for your money to be accessible and secure. There is more information on their website if you are interested in learning more.
Common Reasons You May Need an Emergency Fund
There are many unexpected situations that can lead to a financial emergency.
Unexpected Medical Expenses
Out-of-pocket expenses like deductibles, copays, and prescription drugs really add up, especially if you get hurt and need unexpected medical attention.
Car Repair Expenses
If your only means of transport is your car and it needs a transmission or alternator replacement, you risk losing your income while also needing the money for the repair.
Job Loss or Income Reduction
If you lose your job or have a pay reduction, you still have to pay for your normal everyday expenses like rent and groceries. An emergency fund can help you pay for normal everyday expenses while you look for a new job or wait for your next paycheck.
Unexpected Home Repairs
Scheduling regular maintenance for your home is one thing, but factoring in the unexpected repairs is another challenge altogether. Water heaters, air conditioners and even major repairs for plumbing can suddenly stop working. Having an emergency repair fund means you won’t have to choose between making your mortgage payment or other essential payments and covering the cost of the repair.
How to Start Building an Emergency Fund
It’s a myth that you need to make one large savings announcement to save thousands. Small repeatable actions, when combined with the right amount of automation, will get you there.
1. Start Small
Saving for a large target, like several months’ expenses, can feel daunting when you are starting from nothing. Set smaller targets. The first target can be $500, then $1000, then $1500, etc. Saving $25 a week equals $1300 in a year. The exact number isn’t important, as long as you are moving in the right direction.
2. Save Automatically
Have a set amount transferred from your checking to your savings account after every paycheck. If your paycheck is bi-monthly, and you transfer $50 each time, that’s a $100 saving a month with zero extra thought needed. Adjust the amount you save based on your income; the goal is to be consistent.
3. Do Some Spring Cleaning
Old electronics, furniture, and clothes can be sold for money. While selling these can be a good way to kick start your savings, you can’t rely on this to do the saving for you.
4. Save a Portion of Any Unexpected Money
When you receive a bonus or gift, you have the opportunity to save money without changing your lifestyle. If you receive a $1000 gift, you could save $700 and spend the rest.
5. Cancel One Unused Recurring Expense
That $15 subscription you don’t use? Cancel it to save $15.
6. Be Careful With Savings Rounds
Banks that save the difference from rounding purchases to the nearest dollar can be a good source of extra savings, but the small amounts usually cannot replace normal savings.
7. Try a Planned No-Spend Weekend
Not spending money for a weekend can really add to your savings.
8. Increase Savings With a Raise
When you get a pay raise, so can your savings. You can still enjoy an increased lifestyle with the raise, but save some money too.
9. Keep Emergency Savings Separate
You are more likely to set aside money for an emergency if it is in a different account from your other savings.
10. Rebuild the Fund After Using It
It is not the case that you have failed if you had to use $1,200 of your $4,000 savings to cover a repair. In this case, your savings was used for its correct purpose, and you should focus on repairing the fund by cutting costs or saving more for a period of time.
Additional Insight Into Managing Your Emergency Savings
Understand the Difference Between an Emergency Fund and a Sinking Fund
Learn the differences between a sinking fund and an emergency fund. A sinking fund is set aside for costs that you expect to happen. If you know that you will have to pay $800 for insurance in 6 months, this is not an emergency, and you should not use your emergency fund.
Adjust Your Emergency Fund Based on Your Situation
How much you should keep in your emergency fund depends on how steady your income is. Someone who has low fixed costs and a steady income may be able to keep a lower amount in their emergency fund compared to someone who has higher varying income.
Your target emergency fund balance should change when your situation changes. You may need to change how much you keep in your emergency fund after you buy a new car or make a large change to your monthly expenses.
Keep Your Emergency Savings Accessible
Being cautious with your emergency fund is important, but some people get so cautious that they end up not using their fund at all. Also, be mindful with taking money out to invest. While you might miss out on bigger gains, you could also lose your money at the worst time.
Common Emergency Fund Mistakes to Avoid
Some common mistakes people make are:
- Thinking that a sinking fund is the same as an emergency fund. Planned expenses should not be a part of your emergency fund.
- Setting an overly difficult goal right away. An example of this would be saving $15,000 from a zero savings goal. You should start with a smaller goal.
- Investing emergency savings with assets that have a lot of change and risk. You could end up selling them at a loss.
- Using credit as your emergency plan. While this might be the easiest option, it is the most expensive.
- Keeping your emergency fund in your checking account. You are more likely to spend it if it is not in a different account.
- Saving too aggressively. You can burnout and stop saving all together.
- Never changing your goal. As your income changes, so should your goal.
Benefits and Drawbacks of Having an Emergency Fund
Some of the benefits are less financial stress, less reliance on debt, more flexibility during income disruptions, protection for other financial goals, and a stronger financial foundation.
Some of the drawbacks are that it takes discipline to set up and maintain, cash grows slower than investments, you might have to cut back on your spending, you have to adjust it sometimes, and staying liquid means lower long-term growth.
The point of an emergency fund is to provide financial stability, not to generate the highest returns.
How an Emergency Fund Fits Into Your Overall Financial Plan
While building your emergency savings, it can also help to organize your other financial goals separately. Planned expenses, everyday spending, long-term investments, and emergency savings all have different purposes.
For additional general reading and online resources, you can also explore Banxia Xiaoshuo as part of your broader online research.
Frequently Asked Questions About Emergency Funds
How much should I put in my emergency fund?
There is not a set amount for everybody. Start with a lower amount and work up to cover a few months of your essential expenses. Increase this amount with your income and/or number of dependents, and/or other resources.
Is $1,000 a good target?
$1,000 is a good initial target, but won’t fully fund your emergency fund. It’s a good starting point.
Where should I keep it?
You need to store your money someplace safe and someplace you can access quickly. A savings account is a good option. In the U.S., make sure your account is FDIC-insured, and in other countries, make sure your account is protected according to your country’s laws.
Would a high-yield savings account be better?
It’s a good idea to keep your money in a high-yield savings account as long as it is accessible and protected. You will want to compare the current yield to other banks and take into account the fees and withdrawal terms.
Emergency fund or paying off debt first?
It is a good idea to keep a small emergency fund and then pay off high-interest debt. After that, you can build your emergency fund some more.
Can I use it for a vacation?
Vacation costs are considered discretionary, so you should save for them separately.
How long does it take to build one?
It all depends on how much you can save each month and how much you need to save. It’s better to save a smaller amount each month for a longer period of time than to try to save a large amount in a short period of time.
Should I keep cash at home?
It’s okay to keep a small amount of cash at home for short term use, but keeping a large amount of cash at home is risky. Keep the majority of it in a safe and accessible account.
What constitutes a true emergency?
An interruption to your income or an expense that you were not expecting constitutes a true emergency if there is nothing that you can do to postpone dealing with it. Examples of this are having to make a non-budgeted medical expense or losing your job. The vast majority of people would say that an unplanned vacation or a purchase that is not in the budget is not a true emergency.
What happens if I use my emergency fund?
Your emergency fund should be used for the exact situation it is meant to help you with. Using your savings to avoid going into debt keeps your fund’s purpose fulfilled. Once your financial situation improves, you should work to restore your fund as soon as you can.
Final Thoughts on Building an Emergency Fund
While saving for your emergency fund, you can still make changes to your lifestyle to account for surprises. Having an active goal makes it easier to justify changes to your lifestyle. You should also save money through payroll deductions and save it in a separate account to prevent yourself from spending it.
Your goals should always be relevant and should change to account for your new situation. Having a small emergency fund is better than having no emergency fund at all. Consistent and small contributions will grow the fund and give you financial security in the future.
One Comment