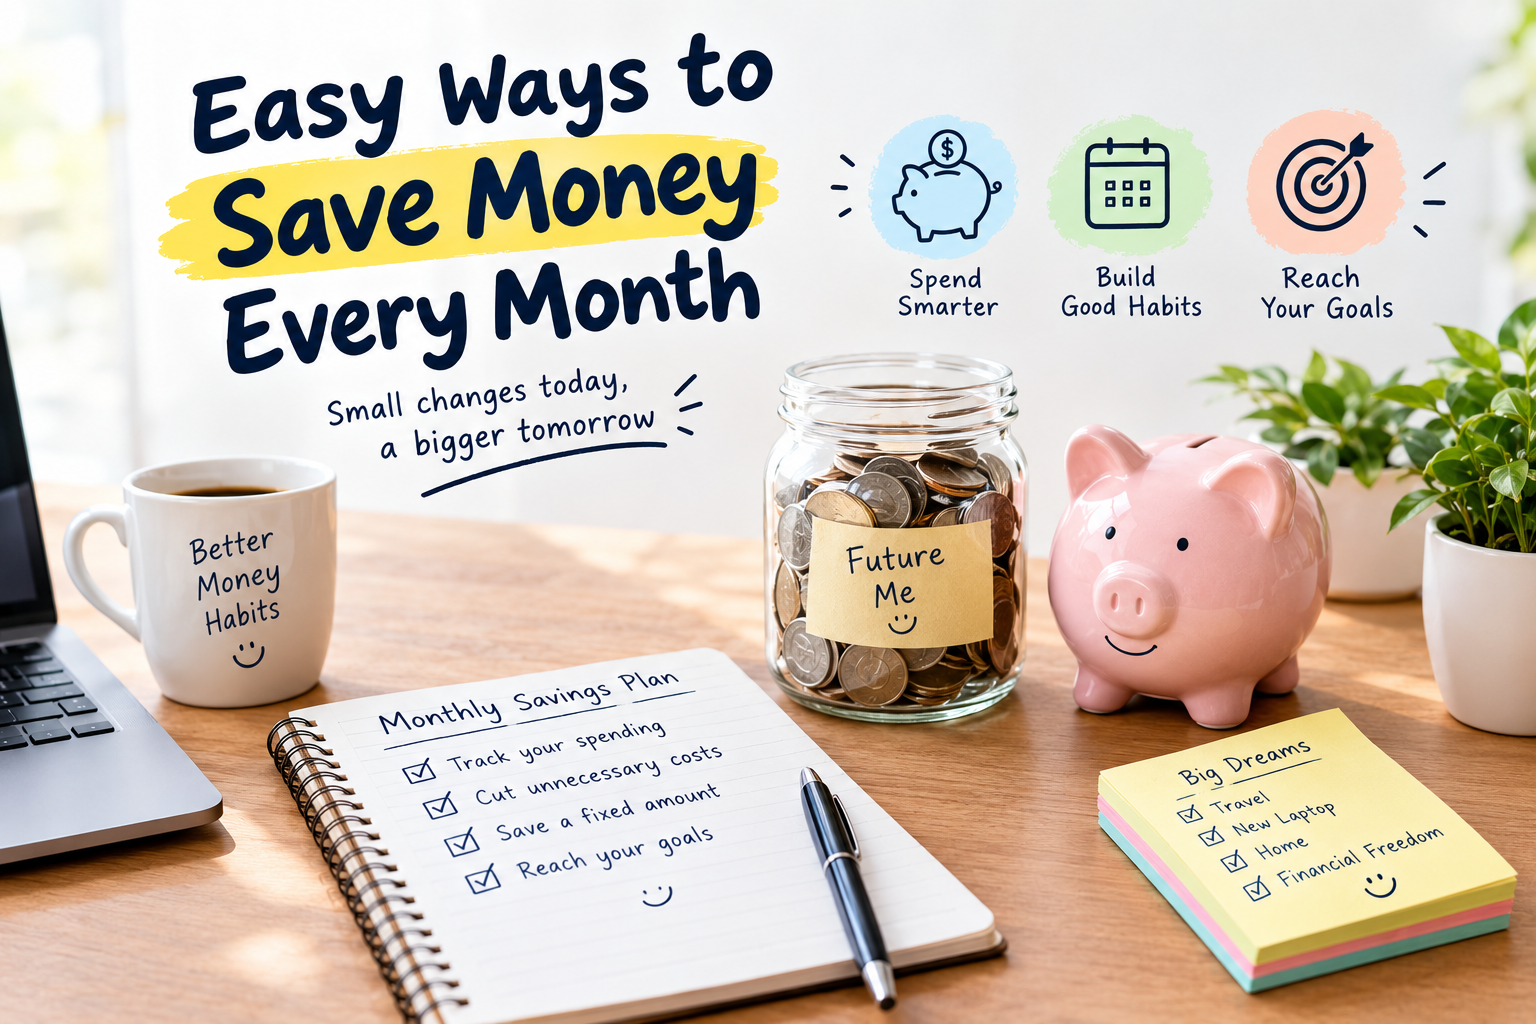
Easy Ways to Save Money Every Month
Saving money sounds simple until everyday expenses start adding up. A coffee here, a food delivery there, a subscription you forgot about-and suddenly the money you thought you had left at the end of the month is gone. For many people, the problem is not earning too little; it is simply difficult to see where small expenses are quietly eating into the budget.
The good news is that saving does not always require major lifestyle changes. The Easy Ways to Save Money Every Month often involve small decisions that are repeated consistently. You might reduce an unnecessary subscription, plan your grocery shopping more carefully, or set aside a small amount immediately after getting paid.
The challenge is knowing which changes will actually make a difference without making your daily life miserable. Some people create unrealistic budgets and abandon them after a few weeks. Others try to save whatever is left over, only to discover there is nothing left.
Before changing your spending habits, it helps to understand why saving can be difficult in the first place. Once you recognize those patterns, practical ways to build monthly savings become much easier to identify.
What Does It Mean to Save Money Every Month?
Saving money every month simply means deliberately keeping part of your income instead of spending all of it. The amount does not have to be large. What matters most for beginners is creating a repeatable habit.
For example, imagine someone earns ₹40,000 a month. After rent, groceries, transportation, bills, and other expenses, they may decide to set aside ₹2,000 each month. That money could eventually become an emergency fund, help pay for a planned purchase, or simply provide more financial breathing room.
Monthly saving can happen in several ways. You can transfer money to a separate savings account, reduce recurring expenses, cook at home more often, compare prices before larger purchases, or create limits for categories where you regularly overspend.
The important distinction is between saving intentionally and simply hoping to spend less. If you wait until the end of the month to see what remains, everyday spending will often consume the available money first.
A simple approach is to treat savings like another monthly expense. If you receive your income on the first of the month, for example, you could move a predetermined amount to savings shortly afterward.
The goal is not to stop enjoying your money. It is to make sure some of it serves your future as well as your present needs.
Why Is It Difficult to Save Money Every Month?
Small Purchases Add Up
A ₹100 or ₹200 purchase may not seem important on its own. The problem appears when similar purchases happen repeatedly.
Buying snacks, ordering drinks, using delivery services, or making small online purchases throughout the month can create a surprisingly large total.
For example, spending ₹150 on small purchases five times a week is roughly ₹3,000 over four weeks. The individual transactions feel minor, but together they can compete with a meaningful monthly savings target.
Some costs are difficult to reduce quickly.
Rent, loan payments, school fees, insurance, utilities, and transportation can consume a significant portion of someone’s income before discretionary spending even begins.
This matters because someone may believe they have a spending problem when their biggest challenge is actually that fixed expenses leave little flexibility.
Understanding the difference helps you focus on expenses that can realistically be changed.
Spending Without a Clear Budget
Without some idea of how much is available for different categories, it is easy to spend based on whatever feels affordable at the moment.
For example, you might spend freely during the first two weeks of the month and then become extremely careful during the final week.
A simple spending plan provides boundaries before the money disappears.
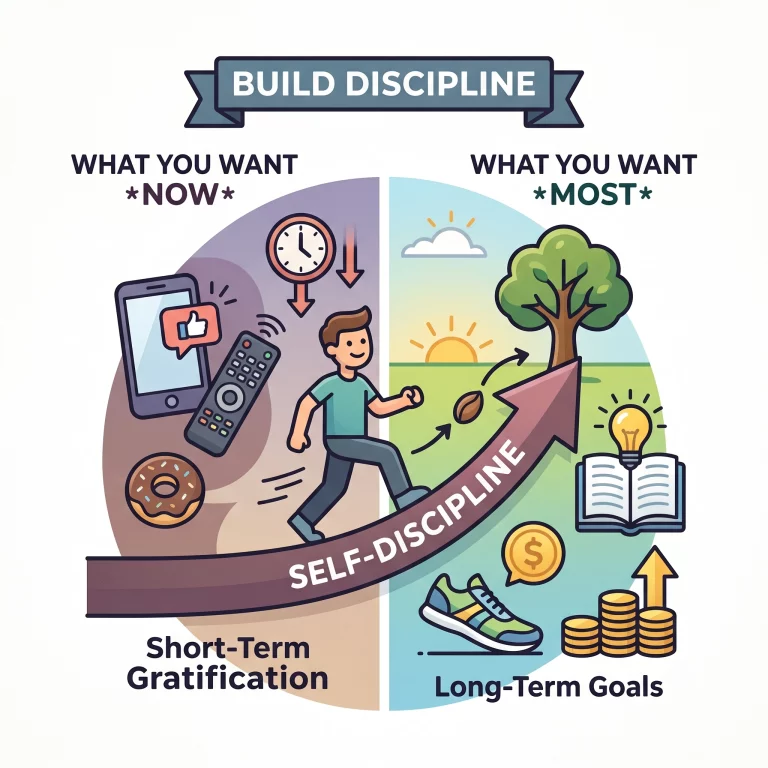
Saving Only What Is Left Over
This is one of the most common patterns.
Someone pays the bills, buys groceries, goes out, shops online, and handles other expenses. At the end of the month, they plan to save whatever remains.
Unfortunately, there may be nothing left.
Saving at the beginning of the month gives the money a specific purpose before it gets absorbed by everyday spending.
Lifestyle Spending Can Increase Gradually
As income increases, spending often increases too.
Someone who receives a raise may immediately upgrade their phone, eat at more expensive restaurants, or subscribe to additional services.
There is nothing inherently wrong with enjoying higher income, but if every increase in earnings produces an equal increase in spending, savings may never improve.
Unexpected Expenses Interrupt Plans
Car repairs, medical bills, appliance replacements, travel, or family emergencies can disrupt even a good budget.
Without an emergency cushion, people may have to use credit or borrow money when something unexpected happens.
That is why saving is not only about reaching a future goal. Some savings provide protection against ordinary financial surprises.
Best Ways to Save Money Every Month
1. Track Your Spending for One Month
Before making major changes, find out where your money actually goes.
For one month, record your regular expenses. Include groceries, transportation, subscriptions, online shopping, eating out, entertainment, and small purchases.
You do not need complicated software. A spreadsheet, notes app, or simple budgeting application can work.
The reason this helps is that people often underestimate irregular spending. You might think you spend ₹1,000 a month on takeout and discover the real number is closer to ₹2,500.
Once you see the numbers, you can make decisions based on reality instead of guesses.
Common mistake: Trying to reduce every category immediately.
Better approach: Track first, then choose two or three categories with the most realistic potential for savings.
2. Pay Yourself First
Instead of waiting until the end of the month, set aside your savings soon after receiving your income.
For example, if you want to save ₹3,000 each month, move that amount into a separate savings account shortly after payday.
This works because the money is removed from the spending pool before you have an opportunity to use it elsewhere.
If ₹3,000 feels too high, start with ₹500 or ₹1,000. A sustainable amount is better than an ambitious target you cannot maintain.
Common mistake: Setting a savings amount that leaves too little money for essential expenses.
Better approach: Choose an amount that fits your actual budget and adjust it as your circumstances change.
3. Cancel Subscriptions You Rarely Use
Recurring payments are easy to forget because the money leaves your account automatically.
Check your bank or card statements and make a list of subscriptions. Look for streaming services, apps, memberships, cloud storage plans, gaming services, and other recurring charges.
If you pay ₹500 each month for a service you rarely use, cancelling it saves ₹6,000 over a year.
You do not need to cancel everything. Keep the subscriptions you genuinely enjoy or need and remove the ones that no longer provide enough value.
Common mistake: Keeping a subscription because it is “only” a few hundred rupees.
Better approach: Multiply the monthly cost by 12. The annual figure makes small recurring expenses easier to evaluate.
4. Plan Your Grocery Shopping
Food spending can become unpredictable when shopping is done without a plan.
Before visiting the supermarket, check what you already have at home. Then create a simple list based on meals you expect to prepare.
For example, if you already have rice, lentils, spices, and vegetables, buying another large collection of ingredients may create waste.
Planning also makes it easier to compare prices and avoid impulse purchases.
Common mistake: Shopping while hungry and adding whatever looks appealing.
Better approach: Eat before shopping, take a list, and decide which purchases are necessities before entering the store.
5. Create a Waiting Rule for Non-Essential Purchases
Impulse purchases become easier to control when you introduce a short pause.
For smaller purchases, you might wait 24 hours. For expensive items, you could wait a week or longer.
Suppose you see headphones priced at ₹6,000 and immediately want them. Instead of buying them on the spot, write down the model and revisit the decision later.
Sometimes you will still want the product. That is fine. The waiting period simply gives you a chance to decide whether you actually need it.
Common mistake: Treating every discount as a reason to buy.
Better approach: Ask, “Would I still buy this if it were full price?” If the answer is no, the discount may not actually be saving you money.
6. Reduce Food Delivery Without Eliminating It
You do not have to completely stop ordering food.
Instead, create a reasonable limit.
For example, someone who orders food four times a week might reduce it to twice a week and prepare simple meals at home on the other days.
If one delivery costs ₹400 and you avoid six orders in a month, that is approximately ₹2,400 kept in your budget.
The key is choosing a reduction you can live with. A plan that says “never order food again” may work for a few days but become frustrating quickly.
Common mistake: Making extreme rules.
Better approach: Reduce frequency and keep occasional treats as part of the budget.
7. Use a Separate Savings Account
Keeping spending money and savings in the same account can make it tempting to use the money.
A separate savings account creates a psychological boundary.
For example, if your everyday account contains ₹25,000 but your savings account contains ₹5,000 that you have deliberately set aside, you are less likely to treat the entire ₹30,000 as available spending money.
Some people also create separate savings categories for specific goals, such as emergencies, travel, education, or a large purchase.
Common mistake: Moving savings back into the spending account whenever the month gets tight.
Better approach: Build a realistic spending budget so your savings are not constantly being raided.
8. Compare Prices Before Major Purchases
For expensive items, a few minutes of research can make a meaningful difference.
Compare prices from several reputable sellers and check whether you actually need the newest model.
For example, if you need a laptop for basic office work, you may not need the most expensive model available. A previous-generation device that meets your requirements could cost considerably less.
Price comparison is especially useful for electronics, insurance, travel, appliances, and other large purchases.
Common mistake: Comparing only the headline price.
Better approach: Consider the total cost, warranty, delivery charges, quality, and expected lifespan.
9. Give Yourself a Monthly Fun Budget
Saving becomes difficult when the budget contains nothing enjoyable.
Instead of trying to eliminate entertainment spending, give it a limit.
For example, you might decide that ₹2,000 per month is available for restaurants, movies, games, hobbies, or other non-essential activities.
Once the amount is planned, you can spend it without feeling guilty while still protecting your savings goal.
This approach can be more sustainable than constantly telling yourself that you cannot spend anything.
Common mistake: Treating a budget as punishment.
Better approach: Include reasonable spending for things you enjoy.
10. Increase Your Savings When Your Income Rises
A raise, bonus, freelance payment, or additional income can provide an opportunity to improve savings.
You do not have to save the entire increase.
For example, if your monthly income rises by ₹5,000, you could direct ₹2,500 toward savings and use the remaining ₹2,500 for lifestyle improvements or other priorities.
This helps prevent every increase in income from immediately becoming additional spending.
Common mistake: Increasing expenses by the full amount of every raise.
Better approach: Decide in advance what percentage of additional income will go toward savings.
Expert Tips
Use a “No-Spend” Category Carefully
A no-spend challenge can be useful for identifying unnecessary purchases, but it should not mean avoiding essential expenses.
Instead of declaring an entire month a no-spend month, try a weekend or a specific category. For example, avoid online shopping for seven days and see how often you feel the urge to buy something.
This can reveal spending triggers without creating an unrealistic financial rule.
Look at Annual Costs, Not Just Monthly Costs
A monthly charge can appear harmless when viewed in isolation.
Turn it into an annual number.
A ₹299 subscription costs about ₹3,588 per year. A ₹799 monthly service costs nearly ₹9,600 annually.
This simple calculation can change how you evaluate recurring expenses.
Create a Small Buffer in Your Budget
Do not allocate every rupee to a specific category.
Leave some room for unexpected costs. A budget that assumes every month will be perfectly predictable is difficult to maintain.
For example, an unexpected ₹1,000 expense should not completely destroy your plan.
Use Separate Goals for Different Types of Savings
An emergency fund and a vacation fund serve different purposes.
If all savings are mixed together, you may be tempted to spend emergency money on something planned.
Naming your savings goals can make the purpose clearer and help you think twice before withdrawing the money.
Review Your Budget Monthly, Not Constantly
You do not need to check every transaction ten times a day.
Set aside 20 to 30 minutes near the end of each month to review what happened.
Look at what you spent, where you went over budget, and what worked well.
If grocery spending was lower but transportation was higher, for example, you can adjust the following month’s plan rather than abandoning the entire budget.
Common Mistakes to Avoid
- Trying to save too much too quickly: An unrealistic savings target can leave you short of money for essentials. Start with an amount you can maintain consistently.
- Ignoring small recurring expenses: Several small subscriptions or frequent purchases can become a significant annual cost. Review recurring payments regularly.
- Using credit to maintain a savings goal: Saving money while simultaneously creating expensive debt can defeat the purpose. Cover essential obligations first.
- Making the budget overly restrictive: A plan with no room for entertainment or personal spending can become difficult to maintain. Include reasonable discretionary spending.
- Forgetting irregular expenses: Annual insurance payments, repairs, gifts, and other occasional costs can disrupt a monthly budget. Set aside money for predictable irregular expenses.
- Treating discounts as automatic savings: Spending ₹5,000 on something you did not need is not saving ₹2,000 just because the original price was ₹7,000.
- Comparing your budget with someone else’s: Income, housing costs, family responsibilities, and priorities differ. Build a plan around your own circumstances.
- Giving up after one bad month: Unexpected expenses happen. Review what went wrong, adjust the plan, and continue rather than abandoning the habit completely.
Pros and Cons of Easy Ways to Save Money Every Month
Pros
- Builds financial discipline: Regular saving turns money management into a repeatable habit.
- Creates an emergency cushion: Savings can help cover unexpected expenses without immediately relying on borrowing.
- Reduces financial stress: Having some money set aside can provide greater flexibility when expenses change.
- Supports future goals: Monthly savings can contribute toward travel, education, a major purchase, or other priorities.
- Does not require major lifestyle changes: Small adjustments can sometimes produce meaningful results over time.
Cons
- Requires consistency: Saving only occasionally may not produce the results you expect.
- May require lifestyle adjustments: Reducing certain expenses can mean changing established habits.
- Unexpected expenses can interrupt progress: Repairs, emergencies, and other costs may require you to use savings.
- Very small savings may feel slow: Beginners may become discouraged when progress is not immediately visible.
- Not every expense can be reduced: Rent, debt payments, healthcare, and other essential costs may have limited flexibility.
Frequently Asked Questions
How much money should I save every month?
There is no single amount that works for everyone. Your ideal savings target depends on income, essential expenses, debt, financial goals, and existing savings. A beginner might start with a manageable fixed amount rather than choosing an aggressive target. The important thing is that the amount fits comfortably within your budget. You can increase it later as your income or financial situation changes.
How can I save money if my income is low?
Start by separating essential expenses from flexible spending. Track where your money goes, then look for smaller areas where you have some control. Saving ₹500 consistently is still better than setting a ₹5,000 target that forces you to borrow money later. Also consider irregular income opportunities, such as occasional freelance work, while making sure essential expenses remain your first priority.
What is the easiest expense to cut?
For many people, optional recurring expenses are among the easiest to review because cancelling one does not affect essential needs. Examples include unused subscriptions, frequent food delivery, impulse shopping, or memberships you rarely use. However, the easiest category depends on your lifestyle. Review your spending first rather than assuming that one particular expense is responsible for your financial problems.
How can I save money without feeling deprived?
Build your budget around your real life instead of eliminating everything enjoyable. Give yourself a reasonable amount for entertainment, eating out, hobbies, or personal purchases. The goal is to control spending rather than remove all discretionary spending. You may also find it easier to reduce the frequency of expensive habits instead of stopping them completely.
Is it better to save weekly or monthly?
Either approach can work. Monthly saving is convenient for people who receive a regular monthly salary, while weekly saving can make the process feel smaller and more manageable. For example, someone aiming to save ₹4,000 per month could think of it as roughly ₹1,000 per week. The best schedule is the one that matches when you receive income and how you normally manage expenses.
How can I stop impulse buying?
Create a delay between seeing something and purchasing it. A 24-hour rule works well for smaller non-essential purchases, while expensive items may deserve a longer waiting period. Remove saved payment details from shopping websites if they make purchases too easy. You can also keep a wish list rather than buying immediately. After several days, you may discover that some items no longer seem necessary.
Should I save money or pay off debt first?
The answer depends on the type of debt, its interest rate, your emergency savings, and your overall financial situation. High-interest debt can become increasingly expensive, while having no emergency savings can force you to borrow when an unexpected expense appears. A balanced approach may involve maintaining a basic emergency cushion while directing additional money toward expensive debt.
How can I save money on groceries each month?
Start by checking what you already have, planning several meals, and making a shopping list. Compare prices and consider store brands where the quality meets your needs. Avoid buying large quantities simply because something is discounted if you are unlikely to use it. Reducing food waste can also make a difference because food thrown away represents money that was spent without providing much value.
What should I do if I keep spending my savings?
First, identify why you are withdrawing the money. If it is happening because of regular expenses, your monthly budget may need adjustment. If the withdrawals are for genuine emergencies, the savings may be doing exactly what they are supposed to do. Consider keeping emergency savings separate from money intended for planned purchases so that one goal does not constantly compete with another.
How long does it take to build a good saving habit?
The timeline varies from person to person. A useful starting point is to focus on repeating the behavior rather than waiting for a particular number of months. Automating a small transfer after payday can reduce the effort required to remember. Once the habit becomes normal, you can review the amount and increase it when your budget allows. Consistency generally matters more than starting with a large amount.
Conclusion
Saving money every month does not require a perfect budget or a dramatic change in your lifestyle. For most beginners, the process starts with something much simpler: understanding where the money is going and making a few deliberate changes.
Track your spending, identify unnecessary recurring costs, plan grocery trips, give yourself reasonable limits for discretionary spending, and set aside savings before the money gets absorbed by everyday purchases. Even small amounts can become meaningful when the habit is repeated consistently.
At the same time, do not expect every month to go exactly according to plan. Unexpected expenses happen, and some months will be more expensive than others. A good saving strategy should be flexible enough to survive those situations.
The biggest mistake is waiting for the “perfect” time to start. You do not need to save a huge amount on your first attempt. Start with an amount you can realistically maintain, review your progress regularly, and increase your savings when your circumstances allow.
The goal is not simply to spend less. It is to give your money a clear purpose so that some of today’s income can support tomorrow’s needs and goals.